For decades, loan officers began their mornings facing a mountain of paperwork. Loan applications, credit reports, income statements, and tax returns created an overwhelming volume of information. Manually verifying each document and calculating affordability felt like an endless uphill battle.
With the recent arrival of advanced technologies like Agentic AI, many initially feared that cold, impersonal algorithms would replace years of banking experience. However, the financial industry is quickly discovering a different reality: Agentic AI is not a replacement. It is a powerful ally and a relentless taskmaster that is actively transforming loan processing.
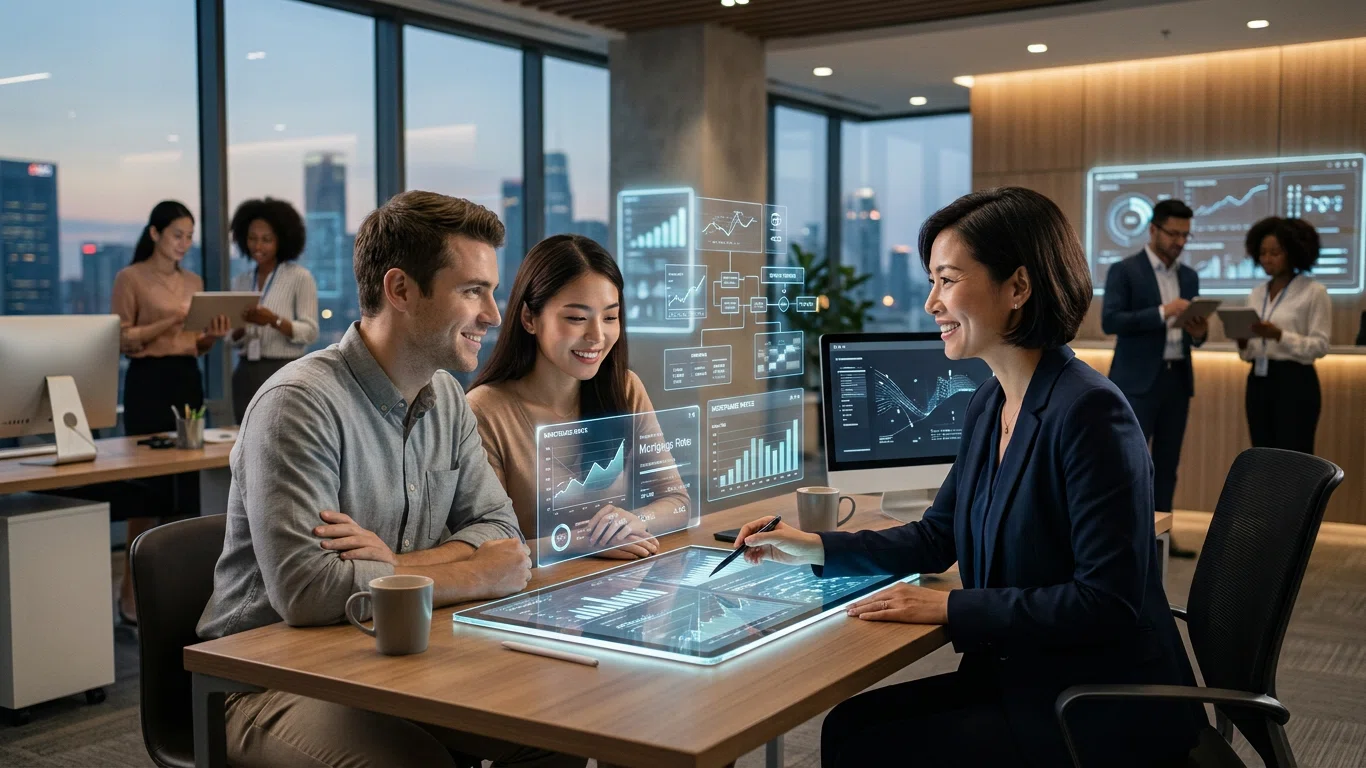
We are witnessing the evolution of the loan officer from a simple number cruncher into an empowered financial advisor.
Balancing the Cost of Automation with Human Capabilities
Transitioning to automated lending is not without its challenges. The true cost of automation is often high, not just in terms of software licensing, but in the internal friction of overhauling legacy systems. Institutions must strike a delicate balance between investing in technology and retaining human capabilities. If lenders build rigid AI systems that attempt to automate the final decision, they risk alienating borrowers and failing compliance audits.
Instead, the most successful approach is a hybrid model. The traditional lending workflow currently breaks down in its first four steps: acquisition, application, bank statement analysis, and credit scoring. Lenders spend hours to days manually parsing a single file, pulling bureau files, and reconciling legal entities by hand. Consequently, on average, it takes five days just to reach the loan disbursement phase. Automating this heavy manual data processing reduces operational costs while freeing up human capital to focus on strategic relationship building and edge-case judgment.
Growth Beyond Singapore
This technological shift is happening rapidly across diverse global markets. While much of the financial press focuses on Singapore’s dominance as a regional fintech hub, this is not necessarily indicative of concentrated development solely within its borders. Many fintech companies establish their headquarters in Singapore to leverage its regulatory clarity and infrastructure, but they actively operate and deploy solutions across several Southeast Asian (SEA) countries.
Countries like Thailand, the Philippines, and Mongolia show great opportunity for fintech operators and the real impact of financial technology is felt when it scales across these diverse, high-growth markets, bringing sophisticated underwriting tools directly to local commercial banks, non-bank lenders, and embedded finance platforms.
Automating the Grind, Elevating the Advisor
To bridge the gap between heavy manual workflows and the need for human-centric advisory, forward-thinking institutions are adopting a new framework: Agentic Credit Intelligence. This approach does not aim to replace the loan officer. Instead, it introduces an intelligent layer that seamlessly extracts, verifies, and scores data to deliver audit-ready credit memos in minutes rather than days.
Solving the lending bottleneck goes beyond basic automation, requiring specialised AI agents to work in concert to handle distinct phases of the loan lifecycle. Here is how this hybrid methodology is reshaping the process:
- Front-End Engagement: Instead of the traditional, endless document-chasing loop, conversational AI can now guide applicants to submit the correct and complete documents in real time.
- Intelligent Risk Verification: Specialised agents cross-check business identities (KYB), verify documents, and instantly flag unusual financial activities or mismatches before the file even reaches a human underwriter.
- AI-Assisted Underwriting: By autonomously analysing income, expenses, and cash flows against specific lending policies, the AI generates an explainable, structured credit memo. The human officer steps in precisely where they are needed most: to review the insights and make the final judgment.
- Continuous Portfolio Monitoring: The workflow extends beyond disbursement. Monitoring agents continuously track repayment behaviours and flag emerging changes in financial health, enabling timely, proactive human intervention.
The operational impact of shifting to this agent-driven, hybrid approach is substantial. Real-world implementations of platforms like AEGIS demonstrate that financial institutions can achieve up to 90% faster credit decisions while reducing manual underwriting effort by 70%. Ultimately, this know-how allows lenders to scale operations efficiently, achieving up to 13 times more underwriting capacity without the need for a proportional growth in headcount.
A Collaborative Future Built on Trust
Ultimately, the integration of Agentic AI platforms represents a paradigm shift in how the financial industry views automation. By confining AI to the gruelling data-extraction and verification tasks, institutions ensure that the loan officer remains firmly in control of the final verdict.
The future of lending is not a fully automated void dictated by black-box algorithms. Instead, it is a highly collaborative environment where AI handles the paperwork, and empowered human experts manage the people.
As fintech continues to evolve across global markets, institutions that embrace this balanced approach will successfully elevate their loan officers from back-office processors to indispensable, strategic advisors. In the end, finance is, and always will be, a business built on human trust.